
Summary
- PPG reported mixed 4Q19 results, with gains from segment earnings growth and improved operating margins offset by weaker volumes.
- Management remains focused on the inorganic growth route, expecting to make four to five acquisitions in 2020 on top of the six acquisitions in 2019.
- The stock is trading at a widening discount to Sherwin-Williams on EBITDA.
- Valuation gap offers an opportunity for longer-term investors to buy into the PPG story at an attractive price.
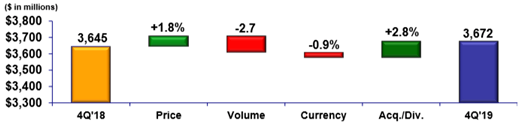
PPG Industries, Inc. (PPG) recently reported a mixed set of 4Q19 numbers - net sales increased 1% YoY on a constant currency basis to $3.67 billion, while volumes were weak and saw a decline of 2.7% YoY. However, despite the weak volumes, PPG continued to execute on its margin recovery measures and was able to improve its 4Q19 EBITDA margins by 160 bps YoY. Looking ahead, the company guided to 1Q20 EPS range of $1.32-$1.42, much lower than consensus' $1.53, which likely implies an overly cautious stance on the future. I believe PPG is well-positioned to drive volume increases in 2020, given the backdrop of an improving economic outlook, improved raw material prices, and a modest scope for further product price increment. With the multiple discount to Sherwin-Williams (NYSE:SHW) widening to historically high levels, PPG shares trade at attractive valuations. Along with the prospect of a re-rating, ongoing share repurchases provide an additional tailwind to EPS, making PPG a compelling opportunity.
A Closer Look at the Results
Sales were driven by price increase and accretive acquisitions: 4Q19 net sales rose 1% YoY on a constant currency basis to $3.67 billion, driven by an increase of 1.8% in selling prices, offset by weaker volumes, which saw a decline of 2.7% YoY. Notably, the acquisitions of SEM, Whitford, Hemmelrath, Dexmet, and Texstars increased net sales by 2.8%, or about $100 million, in the quarter. Foreign currency translation had a negative impact, reducing the quarter's sales by 0.9% or ~$30 million.
Source: Company Presentation
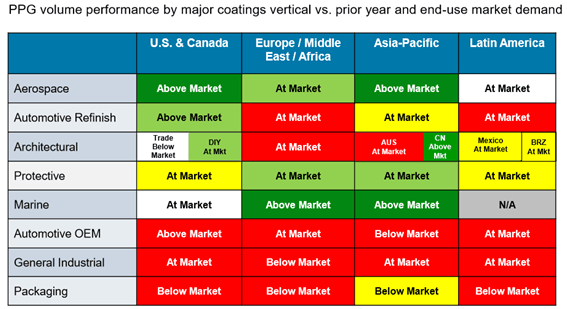
Consistently weaker volumes: Volumes continued to decrease for the 5th straight quarter, declining 2.7% YoY in 4Q19. Industrial Coatings segment saw its volumes decrease by ~6% YoY in the quarter, impacted by soft industrial demand due to contracting manufacturing activity across the US, EMEA, and APAC. The auto OEM volumes declined mid-single digits due to longer than normal customer production shut-downs in EMEA and decline in automotive builds in APAC; packaging coatings volumes declined mid-single digit on account of lower demand for canned food products and potentially some loss in market share; and general industrial coatings volume declined on lower demand for coil, general finishes, and other end-use products. Performance Coatings segment's volumes remained flat YoY and saw modest same-store sales growth in the US, offset by lower European retail volumes.
Source: Company Presentation
Going forward, PPG should see some growth in volumes. China saw some general industrial demand improvement in 4Q19, although, in the near term, it is most likely to be overshadowed by a soft auto demand, and any signs of a rebound in auto sales are not likely to be visible until the Chinese New Year, at the earliest. In EMEA, industrial and architectural demand is likely to remain weak, while automotive OEM coatings demand is likely to remain volatile on account of the impending change in auto emission standards. However, given the easier comparisons, automotive refinish volume should see some growth in the region. Architectural demand is broadly positive in North America, and it is expected that PPG will continue to gain share in aerospace (however, a Boeing (NYSE:BA) production slowdown will likely slow down the volume growth). Additionally, PPG is likely to see some volume improvement in Latin and Central America with the US, Canada and Mexico trade agreement acting as a catalyst for better economic growth in 2020.
Profitability improves from operating margin recovery measures: Despite weak volumes, PPG was able to improve its earnings with continued execution of margin recovery measures like higher pricing, cost savings programs (savings of over $20 million in 4Q19 and $85 million in FY19) and business portfolio optimization with accretive acquisitions. The company's gross margin saw an expansion of 250 bps YoY to 42.5% in 4Q19 - the 4th straight quarter of expansion following eight quarters of gross margin compression. EBITDA margins increased 160 bps YoY during the quarter to 15.2%, while adjusted net income came in at $313 million or $1.31 per share, up 14% YoY.

