
Summary
- The company has fantastic brands but not a clear strategy.
- The downside potential is small, but there is not much upside potential.
- It might come a time to get it, but not today.
Kraft Heinz (KHC) is expected to deliver treacherous revenue growth next year, and the market estimates it will be growing humbly in the following years.
Investing in the company presents a bland risk-reward proposition with low downside but equally low upside potential at a high price. The high dividends its delivers are the most exciting factor of the stock.
Kraft Heinz has legacy brands that carry enormous value. However, there is not a clear strategy or vision to leverage the company's size and brands towards progress. The company might keep the dividend and maintain price, but it is unlikely to outperform the market.
No way to go
The slides of the Q3 earnings show that the company is giving the first step towards forming a strong strategy and identify the most significant issues and inefficiencies that are holding the company back. It is an excellent first step, but it is late only to start making diagnostics. It has been over four years since the merger, and with the past year's trend of the stock, it seems to be late to be making the first steps.
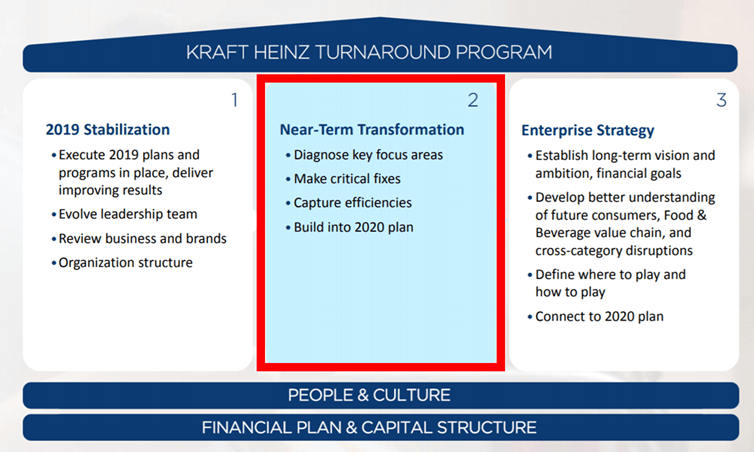
Source: Seeking Alpha
Examining the list of project scopes, some key points are long term goals that will not show improvements in the next year or years. For example, improving marketing spending is complex. It requires a delicate touch, and it is difficult to evaluate how effective are the new policies. As my past article mentioned, innovation will complicate manufacturing processes and may hurt gross margin, while it might be necessary; it is again a long term play. The sales execution project seems to be very ambitious, and the goal of the most sales departments, the improvement is unlikely to be seen overnight.

